

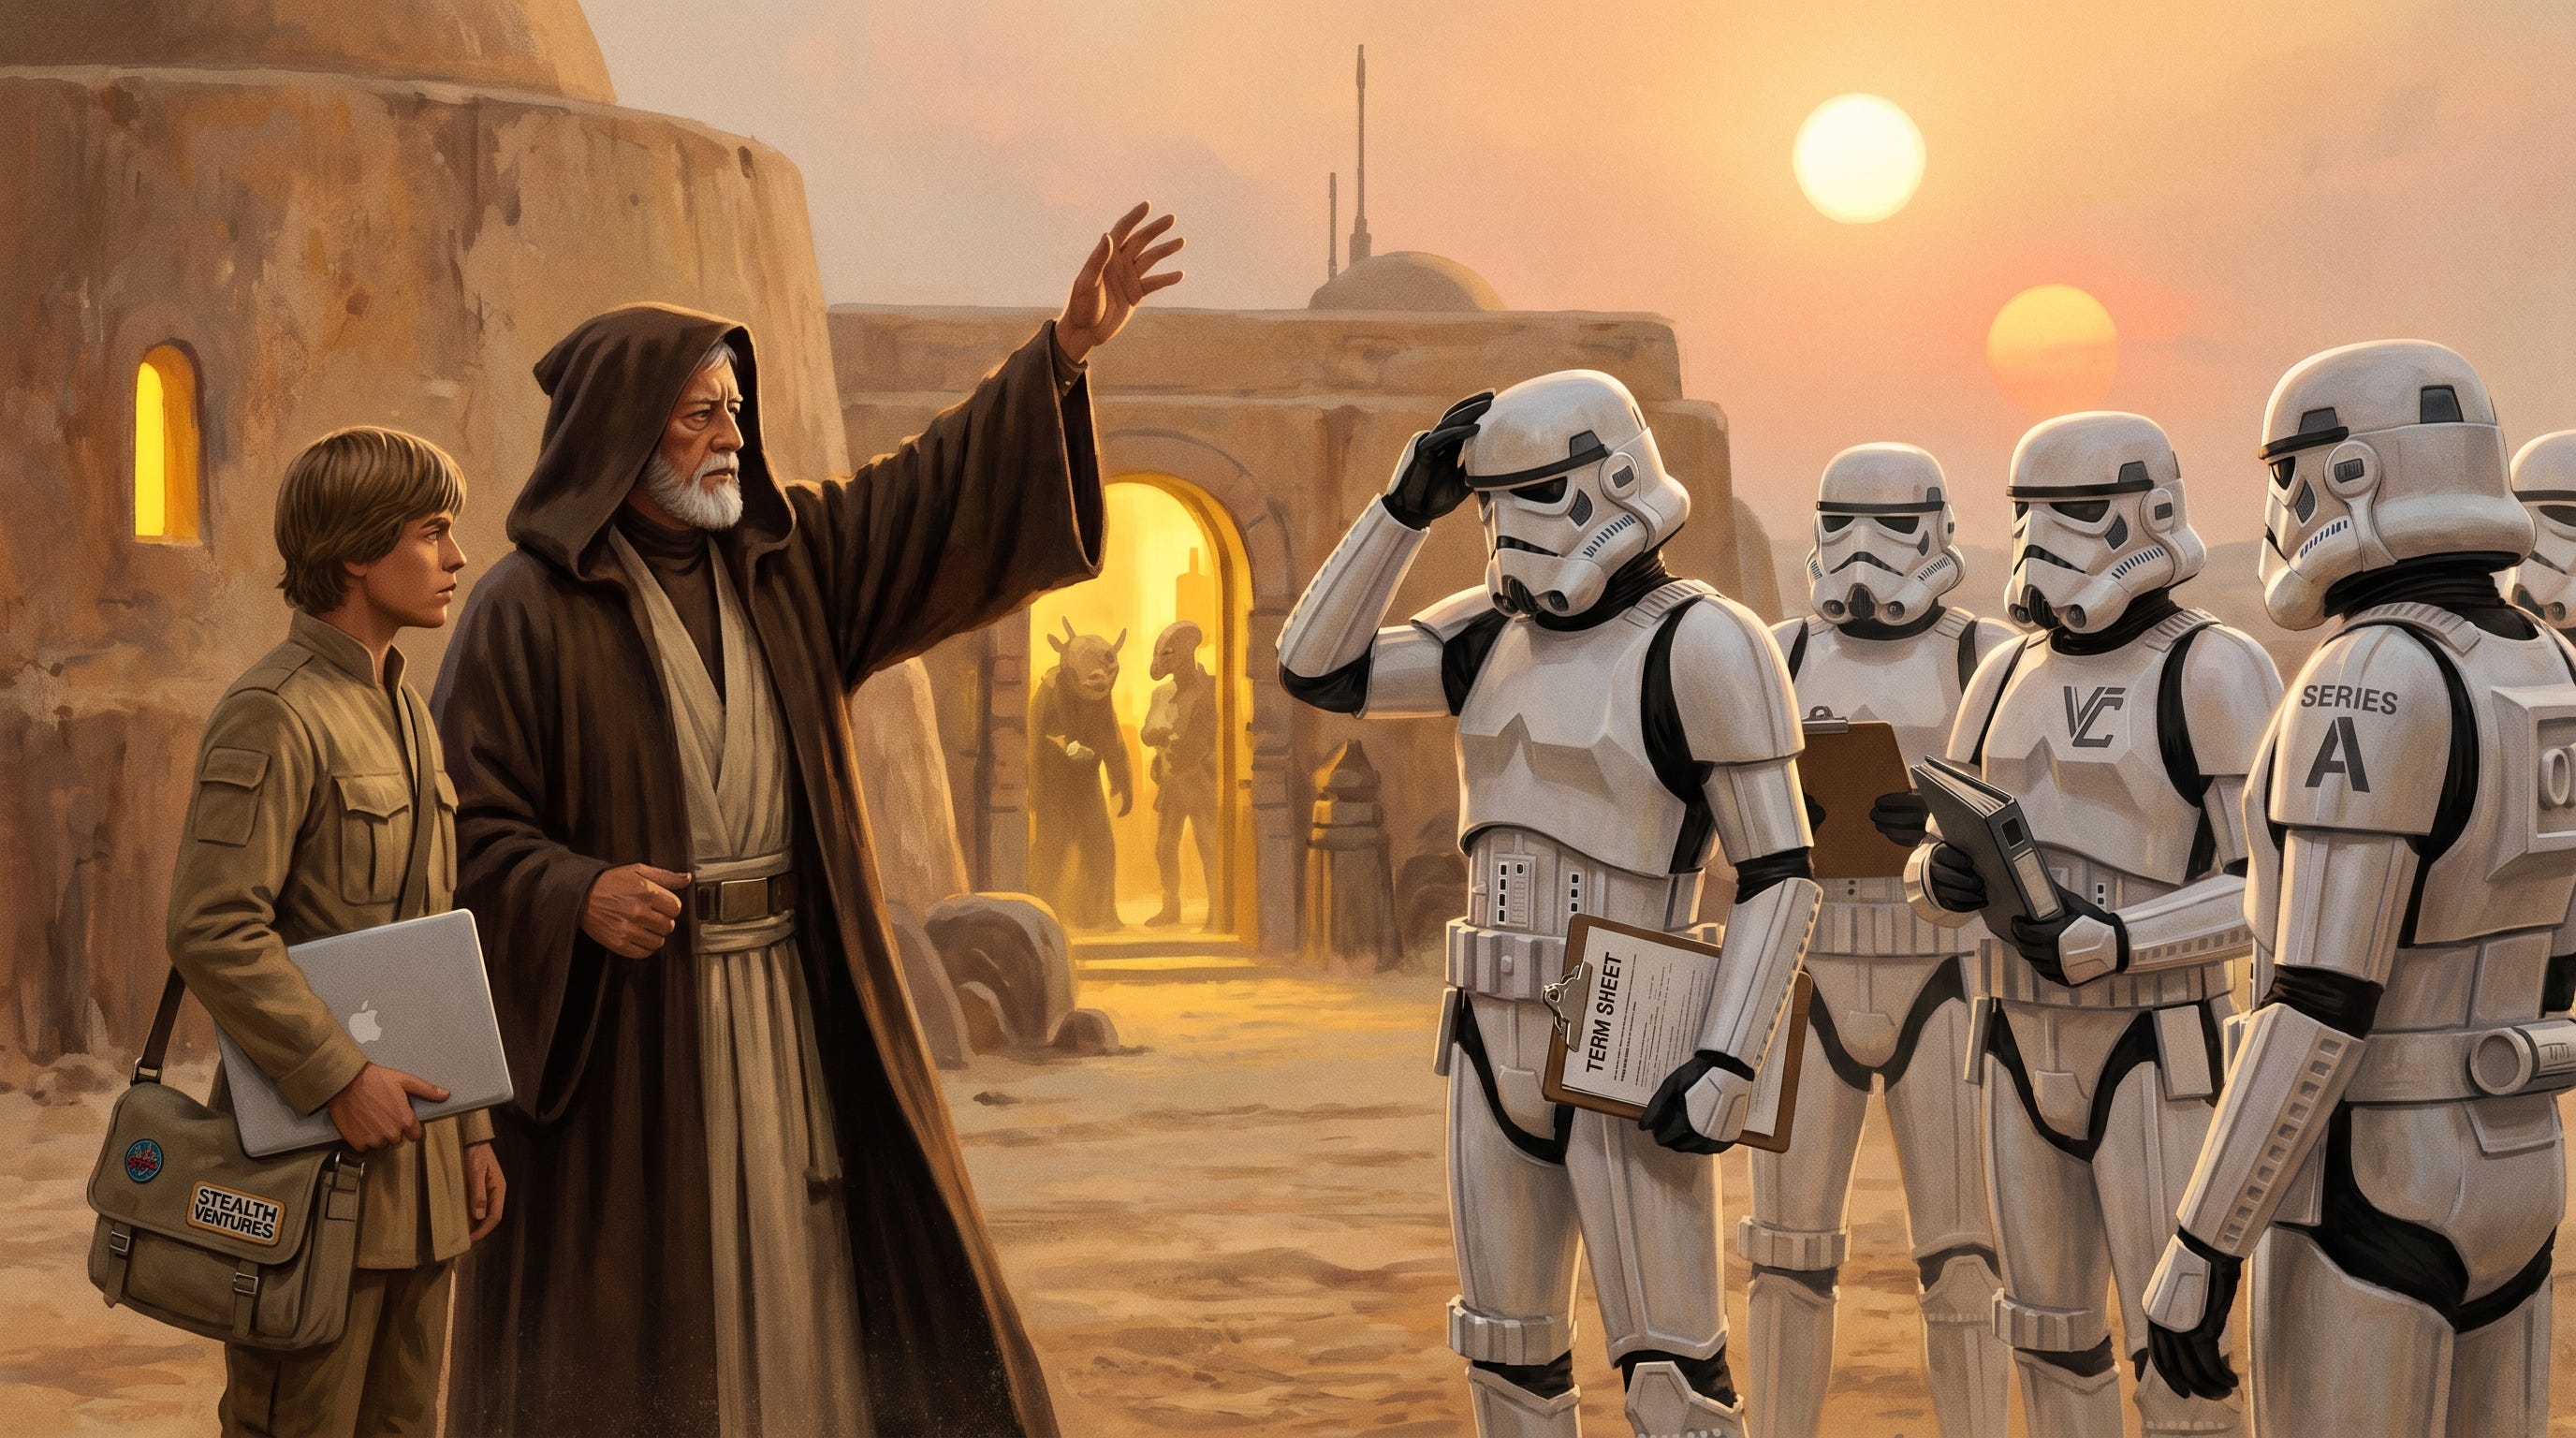
There's a moment in Star Wars where Obi-Wan Kenobi waves his hand at a squad of Imperial stormtroopers and quietly says:
"These aren't the droids you're looking for."
The stormtroopers nod. The party rolls on. Luke stares, confused.
The line works because the stormtroopers had a brief — find specific droids — and the moment Obi-Wan spoke, they pattern-matched to the brief. They saw what they'd been told to see.
Founders walk into fundraising the same way. Every week.
You've been told to "find venture capital (VC) investors." Raise a round. Hit the pitch circuit. Memorize the deck. Practice the 30-second version. You build a list of "top logos." And then you sit across from them and something feels off — the conversation drifts, the feedback is confusing, the interest fades into a polite "keep us posted."
You were talking to the wrong droids.
Why I Wrote This
Eight years ago, I was EVP of operations at Hootsuite. I left that job three months before my daughter was born. I was working 80 to 100 hours a week in operations. Now I work 30, spread across a portfolio of companies instead of one.
That pivot changed how I think about capital.
Every founder who's ever sat in my office has asked some version of the same question: how do I raise money? Almost none of them should have been asking that first.
The better question is: how do I solve the revenue problem? Instead of solving the capital problem, we work with our founders to solve the revenue problem.
Capital follows revenue. Revenue doesn't follow capital.
My thesis: every founder should get to a million in revenue. If we can impact 10,000 founders, that's $10B in economic activity. It takes 15,000 founders to make one billion-dollar valuation, but that's the wrong metric. Economic activity compounds. Valuation doesn't.
That's why GFV works inside companies, not above them. Venture catalysts, not capitalists. The difference shows up in what we spend time on. A VC's question is where do I deploy capital? My question is where is the revenue stuck?
This article is a cheatsheet on the investor — written for you.
I do this a lot. Cheatsheets on closing enterprise deals before you have SOC2. On fundraising for crazy wild ideas. On building a sales pipeline with AI. This one's on the capital room.
A VC writes the cheatsheet for the investment committee. A venture catalyst writes it for the founder.
Once you can read the investor room, you stop trying to convince the wrong ones. You start finding the ones whose mandate was already looking for you.
Trust Is Velocity
Fundraising is foreign territory the first time you do it. So is selling. Same skill, different tempo — read the other side's motivation before you try to win them over.
Ask any founder what the challenge of the day is.
The lucky few gripe about org issues or operational headaches because they're growing and the engine brakes are par for the course. I never feel sorry for them. Those are champagne problems.
The majority are constantly behind the eight ball on cash flow, revenue, sales, or funding.
The ones who achieve escape velocity get absorbed into the fabric of the economy — a strategic acquisition, a private equity (PE) mandate, or a platform of their own.
Founders who struggle share a pattern: they know too little about investor motivations and expectations. That's what the next sections fix.
The Moment a Founder Stops Pitching VCs
I recently talked to a founder who was raising. He said this to me, almost verbatim:
"My deal isn't a venture deal. I'm looking for family offices who want long-term flowing assets in core supply chain materials with landed property investments yielding 9–12% returns. I never plan to exit or sell. Investors will continue to get distributions."
That founder didn't need this cheatsheet.
He already understood what kind of capital his business could support. He knew the return profile his investors would see. He knew the risk tolerance it matched. He knew which room to walk into. And just as importantly — he knew which rooms to walk past.
If you can spew out something like that about your startup — even the version that says "you may never make money on this, it's a risk, but here's the math from our traction to date" — you're ready.
If you can't, read on. Because right now you're pitching spreadsheets to angels and believers to credit funds. Both groups are politely walking you out.
How Investors Actually Think
Before you read the tier map, you need the frame underneath it.
Every investor sits somewhere on a risk curve.
On one end: capital that wants to be preserved. Predictable return. Short time horizon. Collateral. Covenants. Priority in the capital stack. Banks, credit funds, real-estate income funds. The investor is buying certainty.
On the other end: capital that wants asymmetric upside. High failure rate. Long time horizon. No collateral. No priority. The investor is buying lottery tickets with portfolio math — they know most of their bets fail, and they're banking on one or two returning the entire fund.
Everything in between is a blend. The seven tiers I'm about to walk through are seven distinct points on that curve. A family office might hold positions in five of them at the same time, weighted by their wealth stage, liquidity needs, and appetite for risk.
The moment you understand where your business fits on that curve, you understand which rooms are open to you.
The Four Numbers Every Investor Tracks
Every return profile in this article uses the same four variables. Here's what they mean and why they matter.
Cash-on-Cash (CoC)
The annual cash return on the money you invested. If someone puts $100K in and receives $10K per year in distributions, their cash-on-cash is 10%. It's the "does this feel like a paycheck?" number. Credit funds, real estate, royalties, and dividend strategies live here. Venture capital doesn't — there's zero cash until exit.
Internal Rate of Return (IRR)
The annualized compound return over the entire holding period, including the final exit. Accounts for timing and terminal value. A $100K investment that returns $1M in ten years is roughly a 26% IRR. It's the investor's report card — what they'll ultimately tell their limited partners they delivered. Every tier gets measured in IRR, but how it's earned differs radically.
Control
How much the investor can steer outcomes. Total control means they run the business. High means board seats, veto rights, strategic involvement. Medium means covenants, milestones, or structured terms that constrain what you can do. Low means they wrote a cheque and have no say. Control and liquidity usually move in opposite directions — the more control an investor holds, the longer they're usually committed.
Liquidity
How fast the investor can get their money back. Public stocks clear in a day. Credit funds return capital on a payment schedule. Real estate unwinds in months to years. Venture equity is a 7-to-10-year lockup, and sometimes the money never comes back. Liquidity is the price of potential return — the more patient the capital, the higher the ceiling.
These four numbers, read together, tell you everything about what kind of investor you're across from. And what they need to hear from you to say yes.
The Seven Tiers Every Investor Works Within
Every investor in the room you're about to enter sits somewhere on the risk curve above. It runs from preservation at the bottom to asymmetric upside at the top. Each tier has its own return math, its own risk posture, its own time horizon, and its own relationship to control.
Your job as a founder is two things:
1. Figure out which tier your business actually fits.
2. Walk into that room with the language that tier uses.
Here's the full map, lowest-risk to highest:
Tier 1 — Wholly Owned Operating Businesses. Cashflow + control. The tier most founders never realize they're pitching.
Tier 2 — Real Estate + Asset-Backed Yield. The sleep-at-night layer. Cap rates, NOI, collateral.
Tier 3 — Private Credit + Structured Debt. Predictable return without operating risk. Most underused fuel in the founder toolkit.
Tier 4 — Royalties + Revenue Streams + SAFeR. Long-duration cashflow without ownership. Where the SAFeR instrument lives.
Tier 5 — Growth Equity + Strategic Minority. Where founders accidentally land when they thought they were raising venture.
Tier 6 — Venture Capital. Asymmetric upside. Long game. No cashflow for a decade.
Tier 7 — Angels and LPs. Belief capital on one side, blind-pool portfolio math on the other — two very different animals.
Below this line is the tier-by-tier playbook:
The full return-profile breakdown for each tier (cash-on-cash, IRR, control, liquidity, time horizon) — what each investor is solving for in their head.
The business-fit diagnostic — three questions that tell you honestly which tier your business belongs in, and a mismatch matrix for the ways founders get it wrong.
Four capital-stack instruments that let you move your deal into a friendlier tier — RBF, SAFeR, structured preferred, milestone tranches, warrant+debt combos.
Five "truth mirror" questions every founder should answer before raising a dollar.
Three summary tables — the capital ladder, investor motive breakdown, red flags by tier.
The VC sub-type appendix — generalist, deep tech, life sciences, climate — and how each one's mandate shapes what they'll fund.
If you've ever walked out of an investor meeting thinking "why didn't that land?" — the answer is in the next 4,000 words.
